What KYC actually checks, and why banks and exchanges both ask
You're halfway through opening an account when up pops "please complete identity verification", and it asks you to upload an ID, take a face scan, and answer a pile of questions. That's KYC. A lot of people feel "this is a hassle, I'm being suspected, why do they need so much of my private information?" That resistance is understandable, but KYC isn't some platform being difficult on purpose—it's a legally required step for financial institutions worldwide. You can't get around it; you can only learn to get through it smoothly.
KYC checks three things: who you are, where you live, and where your money comes from. Banks and exchanges both check all three; what differs is how hard they look at each one and at what point. Once that's clear, you know which documents to have ready in advance and why some get sent back.
01How KYC relates to anti-money laundering (AML)
KYC stands for Know Your Customer. It isn't a standalone step but the entry point of a larger system, AML (Anti-Money Laundering). Money laundering, terror financing and fraud all rely on the financial system to move funds, so countries legislate that banks, exchanges and the like must, when you become a customer, first establish who you are and where your money comes from—keeping bad actors out at the source and making tracing easier later if something goes wrong.
This standard is global. Internationally, FATF (the Financial Action Task Force) sets the framework, and each country writes it into its own law. That's why you'll find the broad shape of KYC very similar whether you open a bank account in Hong Kong or register on some international exchange—they follow the same underlying logic. It also means you won't find a "legit institution that skips KYC": anything that skips it is either a non-compliant grey platform or an outright scam, and the lure of "no verification" usually leads you somewhere far riskier.
Many people read KYC as being watched. An institution that pays to verify every customer takes compliance seriously; a platform that asks nothing at sign-up gives you less to rely on if something goes wrong. Treat strict KYC as a positive signal.
02The three things it checks: identity, address, source of funds
Break KYC open and, whatever the institution, it rarely strays from these three. Understand what each wants and why, and you'll know what to prepare.
| What it checks | Purpose | Common documents |
|---|---|---|
| Identity (who you are) | Confirm the ID is real and matches the person | Passport / ID card, live face recognition |
| Address (where you live) | Confirm your residence and which jurisdiction it falls under | Utility bill, bank statement, lease |
| Source of funds (where the money came from) | Confirm the money is lawful and fits your profile | Payslip, tax records, transaction history |
The first two are easy to grasp. The third, "source of funds", is the one most often overlooked and the one that bothers people most—why ask where my money came from? But from an anti-money-laundering view, that's precisely the core. The institution needs to confirm the money in your account matches your real situation: an ordinary salaried worker suddenly with a large sum of unexplained money flowing in and out sets the system on alert. So when asked to explain your source of funds, don't feel offended; explain it honestly and with evidence—it actually protects you.
Remember this progression: identity (who you are) → proof of address (where you are) → source of funds (does the money make sense). The bar rises as you go, and the larger the amount or the more frequent the activity, the more likely the institution gets to that third one.
03How bank KYC and exchange KYC differ
It's all KYC, but a bank and a crypto exchange feel quite different in practice; knowing how helps you go in prepared.
| Dimension | Traditional bank | Crypto exchange |
|---|---|---|
| Verification method | Often in-branch or video verification | Mostly online upload + face recognition |
| Speed | Slower, mostly manual review | Faster, highly automated |
| Tiers | Account type sets the bar | Verification levels unlock limits |
| Source-of-funds scrutiny | May ask at opening, stricter for large amounts | Loose at entry, tightens at withdrawal / large amounts |
Exchanges commonly use tiered KYC: finish basic verification and you can play with small amounts; to raise your deposit/withdrawal limits and unlock more functions, you do a higher level and supply more documents. That design lets you start fast, but it also means many people hit the stricter check at the exact moment they "want to withdraw a large amount", caught off guard. So the smart move is to do the KYC level that matches your expected usage right at the start, instead of getting stuck on verification when you urgently need the money.
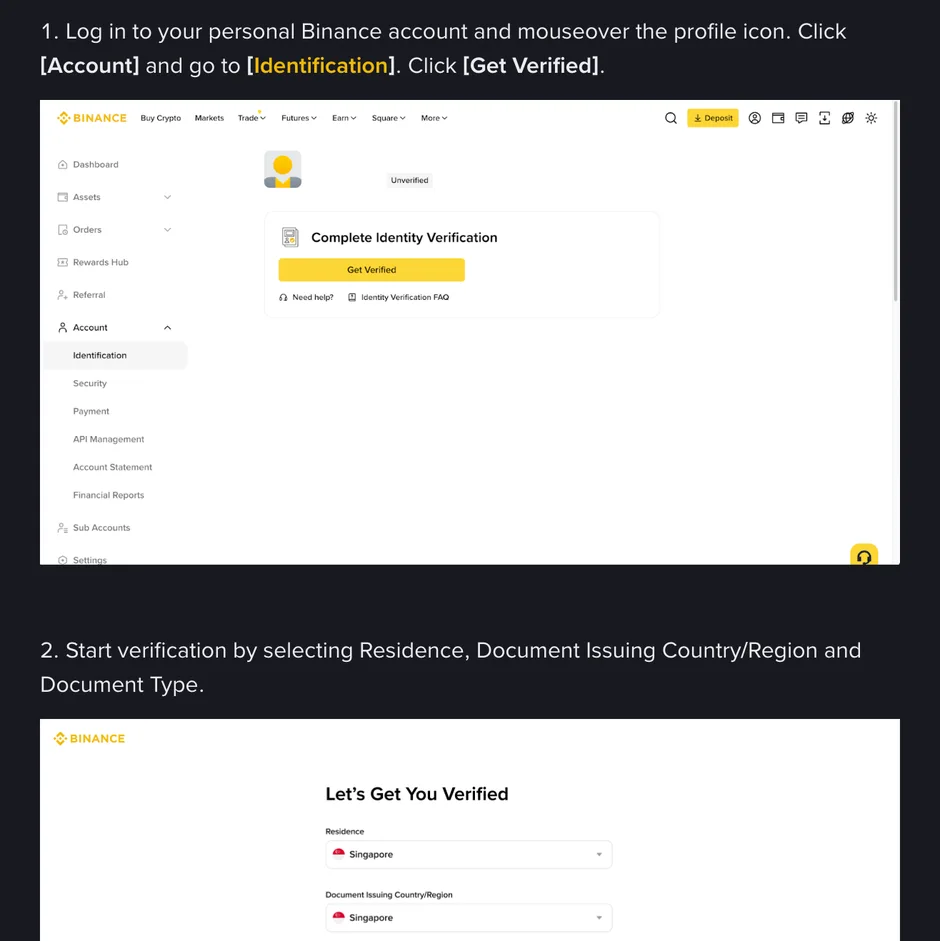
If you're about to register with an exchange, preparing KYC together with the sign-up flow goes much more smoothly. In the complete Binance sign-up guide we walk the whole path from registration to verification, so you can follow along and gather everything in one go, with fewer round trips.
04How to prepare so you pass first time
The most common reason KYC bounces back isn't "you don't qualify", it's "the documents weren't shot well, the details don't match". Get the details below right and your approval rate climbs:
- Clear ID, all four corners, no glare. This is the number-one reason for rejection. Even lighting, laid flat; don't blast it with flash into a white patch, and don't let a finger cover any corner or text.
- Consistent information. The name, date of birth and address you enter must match the ID and the proof of address to the letter. A single punctuation or spelling difference can trigger a manual review.
- Proof of address must be "recent" and "show name and address". Most want a document from the last three months that carries both your full name and your residential address. Too old, or address only without a name, often gets rejected.
- Do face recognition in good light. Face the camera, remove hat and mask, keep the background uncluttered, follow the prompts; no beauty filters.
- Explain source of funds honestly. When asked, back it with documents that match your identity, like payslips or statements; don't invent a source clearly at odds with your situation.
Proof of address is the step that most often snags overseas openings. Different regions accept different documents; in how to open a Hong Kong bank card we've sorted out which proofs of address work well in the HK case, so you can prepare against it if you're going for a HK card.
05Why it keeps getting rejected
Some people submit three or four times and still can't pass, and it's maddening. Beyond the shooting and consistency issues in the last section, repeated rejection often hides one of these:
- An unaccepted document type. For instance, the platform only takes a passport and you uploaded something else; or the ID has expired. Check what it accepts first, then upload.
- Your region isn't in service scope. Some platforms don't open to, or restrict functions for, certain countries/regions, so your verification stalls at the "region" gate—not a document problem, and swapping documents won't help.
- An extra manual review was triggered. When the system spots something odd (the same ID linked to too many accounts, anomalous info), it routes to a human and the cycle lengthens; submitting again now just adds noise, so wait for the review result.
Never use Photoshop to alter ID details, or borrow someone else's ID to pass KYC. Not only will verification certainly fail, your account can be permanently banned and you may face legal liability. When KYC is stuck, the right move is to ask the platform's official support for the reason, not to find a way to "get around" it.
There's also this: KYC passes, but later you're asked for more documents, or the account gets restricted. That usually relates to your funds behaviour and falls under ongoing monitoring. To understand which moves trigger that second review and how to avoid them ahead of time, read our why bank cards get frozen—it's two sides of the same coin as KYC.
06Privacy and data safety: what to watch
KYC asks for your most sensitive personal information—ID, face, address. Hand it to a proper institution with confidence; but keep a few nerves on edge so you don't feed it to places that shouldn't have it.
- Only do KYC through official channels. Stick to the official app and website, and check the URL. Anything asking you to upload ID via a strange link, a third-party page or a private support chat is almost always phishing.
- Don't casually send your ID photo to "support" or a "verification agent". A proper platform's KYC runs through its own encrypted flow; it won't have you send an ID photo to a person via a chat tool. Anyone offering to "pass your KYC for a fee" is either taking your money or stealing your identity.
- Glance at how it uses your data. A proper institution has a privacy policy stating how data is stored, how long it's kept and whether it's shared. One willing to spell that out is more trustworthy than one being vague.
- Watermark your ID photo. If a situation genuinely needs a copy of your ID, add a "for XX use only, invalid elsewhere" watermark to lower the risk of misuse.
Before you submit, check four things: a clear ID photo, details that match the document exactly, a source of funds you can document, and an upload made only in the official app.
- FATF (Financial Action Task Force) — the body that sets the KYC/AML international standards
- Binance Help Center — the identity-verification flow and required documents, per the platform's current pages
- Hong Kong Monetary Authority — regulatory requirements for customer due diligence at banks
- FCA — AML and customer-verification rules for UK financial firms